
VA Loan: How to Buy a 2-to-4 Unit Property in Chicago

Contents
VA Loan 2-to-4 Unit Property: Quick Answer
A VA loan allows you to buy a 2-to-4 unit property in Chicago with no down payment. You must live in one unit and can rent the others.
Rental income may help you qualify and can cover much of your mortgage.
How does a VA loan help veterans buy a 2- to 4-unit property?
A VA loan lets you buy a duplex, triplex, or four-unit property with no down payment while living in one unit.
This creates a powerful opportunity. You live in one unit and rent the others to offset your mortgage.
Key advantages include:
-
No down payment required
-
Competitive interest rates
-
Rental income may help with qualification
Alex’s Story Begins
Alex, a Navy veteran, wanted to buy a Chicago 3-flat.
His goal: reduce his housing cost and build wealth.
His challenge: he didn’t know how to qualify for a mortgage using rental income.
NewCastle showed him exactly how.
He bought a 3-flat in Humboldt Park, moved into one unit, and rented the other two.
Now, his tenants cover most of his mortgage.
Do I have to live in the property if I use a VA loan for a multi-unit home?
Yes. You must live in one of the units as your primary residence.
The VA requires borrowers to move into the home within 60 days after closing and occupy the property for at least 12 months.
After one year, you may convert the property into a full rental if your plans change. This rule allows you to build wealth while meeting VA occupancy requirements.
Are VA loan rates higher for a 2- to 4-unit property?
No. VA loan interest rates are the same for single-family homes and multifamily properties.
However, some lenders charge higher rates for multi-unit properties.
NewCastle Home Loans does not.
We offer the same competitive VA rate for:
-
Single-family homes
-
Two units
-
Three flats
-
Four-unit properties
A lower rate from NewCastle reduces your monthly payment and improves your cash flow.

Can rental income help you qualify for a VA loan on a 2-to-4 unit property?
Yes. You can use projected rental income from the other units to help qualify for a VA loan.
To add the projected rent to your income, you'll need landlord experience or a professional property manager.
If you qualify without rental income from the other units, you do not need prior landlord experience.
If you need the projected rent to qualify, the lender must determine that you can successfully manage the property.
You can meet this requirement in one of two ways:
-
Prior landlord experience: Show that you have experience managing rental property.
- Professional property manager: Hire a qualified property manager to manage the rental units.
NewCastle Home Loans allows first-time landlords to use projected rental income when they meet VA requirements and use a professional property manager.
This can make buying your first 2-to-4 unit property with a VA loan possible even if you have never owned rental property before.
Alex’s Turning Point
Alex's salary and VA disability income alone weren't enough to qualify for the loan.
We added rental income from his two rental units.
That extra income helped him qualify and buy the property.
How much rental income counts for a VA loan for a 2-to-4 unit?
Lenders count 75% of projected rent from the non-occupied units.
The remaining 25% accounts for vacancies and maintenance costs.
A VA-approved appraiser determines fair market rent using the appraisal report.
Example:
Alex's two rental units were expected to rent for $2,500 each per month.
Total rent:
-
$2,500 + $2,500 = $5,000 monthly
We counted 75% of that amount:
-
$5,000 × 75% = $3,750
We added $3,750 to Alex's income when calculating loan approval.
This additional income allowed him to qualify for the mortgage.
Want to see what your numbers look like?
Can first-time landlords qualify for a VA loan on a 2-to-4 unit property?
Yes, first-time landlords can qualify for a VA loan on a 2- to 4-unit property.
The VA does not require landlord experience to purchase a multi-unit home.
However, if you use rental income to qualify, lenders must confirm you can manage the property or have a clear plan in place.
How first-time landlords qualify
Lenders address this by requiring a professional property management agreement rather than prior landlord experience.
A property manager handles:
- Tenant screening
- Rent collection
- Maintenance coordination
- Lease management
This allows you to use rental income without prior landlord history.
Why veterans choose NewCastle
Many lenders require a strict two-year landlord history.
NewCastle does not.
We help first-time landlords qualify by using a property management agreement instead of prior experience.
Landlord Experience vs. Property Manager?
| Scenario | Landlord Experience Required? | Property Manager Required? | Documents Needed |
| Using rental income (experienced landlord) | Yes (2 years) | No | Tax returns, leases, mortgage statements |
| Using rental income (no experience) | No | Yes | Signed property management agreement- licensed property manager (if required)- 6 months PITI reserves |
| Not using rental income | No | No | Standard income documents only (W-2s, pay stubs, etc.) |
Key Rules to Understand
If you use rental income, lenders must confirm you can manage the property.Most lenders require either:
- 2 years of landlord history, or
- A professional property manager
Chicago insight:
In Chicago, property managers typically charge 8% to 12% of monthly rent.
This cost is already built into your rental income analysis.
It does not count as a separate monthly debt for mortgage qualification.
Not sure how to structure your income to qualify?
Book a time to talk with a NewCastle VA loan expert. We’ll show you exactly how to make a multi-unit purchase work.

Do VA loans require cash reserves for a 2- to 4-unit property?
VA loans require cash reserves only if you use rental income to qualify.
You must verify cash reserves equal to six months of your total mortgage payment.
Your total monthly mortgage payment is called PITI, which stands for:
- Principal
- Interest
- Property taxes
- Homeowners insurance
Reserves are not part of your down payment or closing costs. They are funds you keep available as a financial cushion after you buy the property.
Example:
Alex's total monthly PITI was $5,000. He needed $5,000 × 6 months = $30,000 in reserves.
He had more than $50,000 in his retirement account to cover six months of payments.
He documented the funds with a quarterly 401(k) statement.
What assets can you use for VA loan reserves?
You can use bank accounts, retirement funds, and certain investments to meet VA loan reserve requirements.
You must document the funds and have them available after closing.
Assets that can count as reserves
- Checking, savings, money market accounts, and CDs: Use the documented available balance.
- 401(k), IRA, or TSP accounts: Lenders may count 60% of the vested balance, minus any loans against the account.
- Stocks, bonds, and mutual funds: Vested, publicly traded investments may count toward your reserves.
- Cryptocurrency: You must first convert crypto to U.S. dollars and deposit it with a regulated financial institution. You must document ownership and the transfer of funds.
What does not count as VA loan reserves?
- Gift funds from family members or other third parties
- Equity in your home or other real estate
- Cash-out proceeds from the VA refinance being completed
- Cash on hand that cannot be properly documented
- Sweat equity or trade equity
- Pooled savings or private savings clubs
Example
Alex had just over $50,000 vested in his retirement account.
NewCastle Home Loans counted 60% of the vested balance, or $30,000, toward his required VA loan reserves.
The key difference is simple: reserve funds must belong to you, be documented, and remain available after closing.
All required reserve funds must be in the borrower's account before the new VA loan closes.
What is the VA loan limit for a 2-to-4 unit property?
Veterans with full VA entitlement have no official loan limit.
If you qualify, you may finance the entire purchase price with no down payment.
Instead of a cap, lenders evaluate:
-
Income
Loan limits matter only if you've already used part of your VA entitlement.
Example:
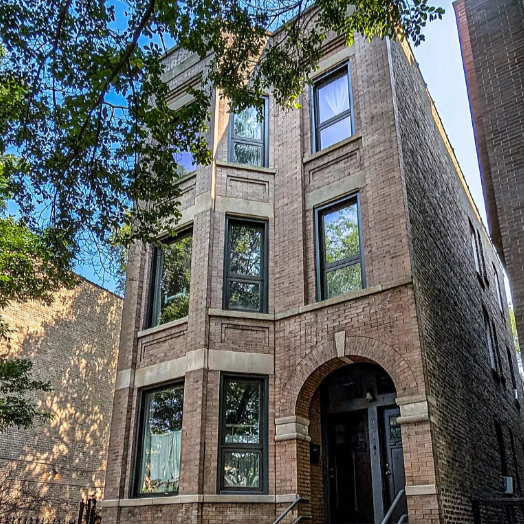
Alex purchased his 3-flat in Humboldt Park for $919,000.
-
Purchase price: $919,000
-
Down payment: $0
-
VA loan amount: $919,000
Because Alex had full VA entitlement and a high income, he financed the entire purchase price.
Chicago insight:
Many veterans buy a Chicago 3-flat, live in one unit, and use rent from the other apartments to cover most of the mortgage payment.
What is the first step to buying a multi-unit property with a VA loan?
The first step is getting pre-approved with a VA-approved lender.
A verified pre-approval confirms:
-
Your maximum purchase price
-
Estimated monthly payment
-
Required cash to close
It also strengthens your offer when competing for Chicago multifamily properties.
Example:
After receiving a verified pre-approval from NewCastle Home Loans, Alex confidently made an offer on his Humboldt Park 3-flat.
His tenants now cover most of the mortgage payment.
He builds equity every month while living nearly rent-free.
Nice place, Alex!
Start your VA multi-unit home search
Buying a 2- to 4-unit property with a VA loan is one of the most powerful wealth-building opportunities available to veterans.
You can combine:
-
No down payment
-
Competitive VA interest rates
-
Rental income from additional units
The result is a home that helps pay for itself.
NewCastle Home Loans has helped Chicago veterans buy homes since 2003. Our local team understands the unique rules for VA multi-unit financing.